
Choosing between a sole trader and a limited company depends on your business income, financial risks, long-term goals and administrative preferences.
A sole trader is generally better for someone starting a small business who wants lower costs and simpler accounting, while a limited company may suit a growing business that needs liability protection and flexibility over how profits are used.
Neither structure is automatically more tax-efficient. Changes to dividend tax rates, National Insurance and company filing fees in 2026 mean business owners should compare the overall financial impact before deciding.
What Is The Difference Between A Sole Trader And A Limited Company?
The main difference between a sole trader and a limited company is their legal identity and how they are taxed.
A sole trader is a self-employed individual who owns and operates a business personally. There is no legal separation between the owner and the business, meaning the individual is generally responsible for business debts and obligations.
A limited company is a separate legal entity registered with Companies House.
The company can own assets, enter contracts, employ staff and pay Corporation Tax on its profits. Shareholders generally benefit from limited liability, although certain circumstances can create personal responsibility.
Both structures can operate businesses of different sizes, employ workers and register for VAT when required. However, their accounting requirements, legal responsibilities and treatment of business income differ considerably.
Sole Trader Vs Limited Company: Key Differences At A Glance
| Feature | Sole Trader | Limited Company |
| Legal Status | Owner and business are legally the same | Separate legal entity |
| Registration | Register with HMRC when required | Incorporate with Companies House |
| Personal Liability | Generally unlimited | Usually limited, with exceptions |
| Tax On Profits | Income Tax and National Insurance | Corporation Tax |
| Owner’s Income | Personal drawings | Salary, dividends or other permitted payments |
| Administration | Relatively simple | More reporting obligations |
| Financial Privacy | Less public disclosure | Certain details publicly available |
| Business Ownership | Owned by one individual | Owned by shareholders |
| Raising Investment | Usually more difficult to offer equity | Can issue shares |
| Business Continuity | Tied more closely to the owner | Company can continue when ownership changes |
For someone starting a small operation, simplicity may be the deciding factor. However, businesses expecting investment, shareholders or substantial contractual liabilities may benefit from incorporating.
Advantages And Disadvantages Of Being A Sole Trader
Operating as a sole trader is one of the simplest ways to start a business in the UK. It is particularly suitable for individuals who want to test an idea before committing to a more complex business structure.
Advantages Of Being A Sole Trader
- Easy Registration: Becoming a sole trader usually involves registering for Self Assessment with HMRC rather than incorporating a company.
- Lower Administrative Costs: Sole traders generally have fewer filing obligations and may spend less on accounting services.
- Direct Access to Profits: Business owners can withdraw money for personal use without processing dividends or director salaries.
- Greater Privacy: Sole traders do not normally have to publish annual accounts on the Companies House register.
- Simple Business Management: Owners make decisions independently without formal shareholder procedures.
Understanding how to set up a sole trader business can help new entrepreneurs begin trading while meeting their HMRC responsibilities.
Disadvantages Of Being A Sole Trader
- Unlimited Personal Liability: Personal savings and assets may be exposed if business debts cannot be paid.
- Limited Investment Opportunities: Sole traders cannot issue company shares to investors.
- Potentially Higher Personal Tax: As profits increase, more income may fall within higher Income Tax bands.
- Business Continuity Challenges: Selling or transferring a sole trader business may require transferring individual assets and contracts.
- Less Flexibility With Tax Timing: Tax generally applies to taxable business profits regardless of how much money the owner withdraws.
While the structure is convenient, it may become less suitable when a business takes on significant financial commitments or develops more complicated ownership needs.
Advantages And Disadvantages Of A Limited Company
A limited company is often preferred by entrepreneurs planning to expand, employ staff, attract shareholders or establish a separate legal identity for their business.
Advantages Of A Limited Company
- Limited Liability Protection: Shareholders are generally responsible for company debts only to the extent of their investment or unpaid share capital.
- Separate Business Identity: The company can own property, enter contracts and operate independently of its shareholders.
- Flexible Profit Management: Profits may be retained within the company or distributed through permitted methods.
- Investment Opportunities: Companies can issue shares to attract investors.
- Business Continuity: Ownership can change through the transfer of shares without necessarily ending the company’s existence.
- Professional Credibility: Some clients and investors may prefer dealing with incorporated businesses.
Disadvantages Of A Limited Company
- Higher Administrative Costs: Companies may require accounting software, professional support and additional reporting.
- Corporation Tax Requirements: Company profits are taxed separately from the owner’s personal income.
- Public Financial Information: Certain accounts and company details must be submitted to Companies House.
- Directors’ Responsibilities: Directors must comply with company law and relevant financial reporting obligations.
- Restrictions On Withdrawals: Company money cannot automatically be treated as personal money.
Business owners considering incorporation should understand how to set up a limited company before deciding whether the benefits justify the additional responsibilities.
Sole Trader Vs Limited Company: Tax Comparison In 2026/27
Taxation is one of the most important differences between the two structures.
Sole traders pay Income Tax and National Insurance on their taxable profits. Limited companies pay Corporation Tax, while directors and shareholders may face additional personal taxes when receiving salaries or dividends.
How Much Tax Does A Sole Trader Pay?
For the 2026/27 tax year, the standard Personal Allowance is £12,570.
The following Income Tax bands apply to non-savings income in England, Wales and Northern Ireland.
| Annual Taxable Income | Income Tax Rate |
| Up To £12,570 | 0% Within The Standard Personal Allowance |
| £12,571–£50,270 | 20% |
| £50,271–£125,140 | 40% |
| Above £125,140 | 45% |
The Personal Allowance reduces by £1 for every £2 of adjusted net income above £100,000. Scotland has different rates and bands for non-savings income.
Sole traders may also pay Class 4 National Insurance:
- 6%: On profits between £12,570 and £50,270.
- 2%: On profits exceeding £50,270.
Class 2 National Insurance is generally treated as paid for qualifying self-employed people with profits at or above the relevant small profits threshold, without requiring a separate payment.
How Much Tax Does A Limited Company Pay?
A limited company pays Corporation Tax on its taxable profits before any remaining profits are distributed as dividends.
| Tax Category | 2026/27 Rate |
| Corporation Tax On Small Profits Up To £50,000 | 19% |
| Corporation Tax Main Rate Above £250,000 | 25% |
| Corporation Tax Between £50,000 And £250,000 | Marginal Relief May Apply |
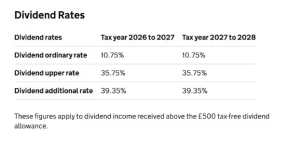
| Basic Dividend Tax Rate | 10.75% |
| Higher Dividend Tax Rate | 35.75% |
| Additional Dividend Tax Rate | 39.35% |
| Annual Dividend Allowance | £500 |
Corporation Tax thresholds may be reduced where companies have associated companies or shorter accounting periods.
Shareholders receiving dividends may pay personal dividend tax after the applicable allowances. Unlike an ordinary salary, dividends are not generally subject to National Insurance.
Directors receiving salaries may also create employer National Insurance liabilities for their company. The standard employer rate is 15% on earnings above the relevant secondary threshold in 2026/27.
Government’s Budget dividend rates:
Government’s budget income tax rate:
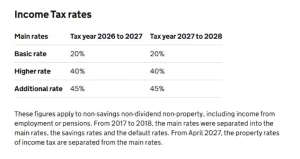
The government’s Budget 2026 rates table confirms the Income Tax and dividend tax rates applying in 2026/27.
Sole Trader Vs Limited Company Take-Home Pay Examples
Comparing take-home income helps demonstrate how the different tax systems affect business owners.
The following examples assume an England-based owner with no other income or special reliefs.
The limited company has one director-shareholder who receives a £12,570 salary and withdraws all remaining post-tax profit as dividends.
Employer National Insurance is included, but other operating costs are excluded.
The company is assumed not to qualify for Employment Allowance, as is generally the case where its only paid employee is the sole director.
| Annual Business Profit | Sole Trader Take-Home Pay | Limited Company Take-Home Pay |
| £30,000 | Approx. £25,468 | Approx. £24,403 |
| £60,000 | Approx. £46,111 | Approx. £46,091 |
| £100,000 | Approx. £69,311 | Approx. £65,210 |
These are illustrative 2026/27 calculations rather than personalised tax quotations.
At £30,000 profit, the sole trader retains more income under the assumptions used. At £60,000, the results are very similar.
At £100,000, the sole trader retains more because the company owner withdraws all available profits and pays the applicable dividend taxes.
However, the comparison could change if company profits are retained for reinvestment, the director takes a different salary or the business qualifies for additional reliefs.
The important distinction is that a limited company does not automatically save tax simply because profits exceed a particular amount.
How Much Does It Cost To Set Up And Run Each Business Structure?
The cost of registration and ongoing compliance can influence which structure is more practical.
A sole trader can normally register through HMRC without paying a government registration fee. Limited companies must pay Companies House fees and meet additional filing requirements.
| Expense | Sole Trader | Limited Company |
| Initial Registration | Usually Free | £100 Online |
| Annual Confirmation Statement | Not Required | £50 Online |
| Annual Accounts Filing | No Companies House Filing | Required |
| Self Assessment | Generally Required When Applicable | May Apply To Directors Personally |
| Corporation Tax Return | Not Required | Required When Applicable |
| Accounting Services | Often Simpler | Usually More Complex |
| Payroll Administration | Required If Employing Staff | May Be Required For Director Salaries |
The Companies House digital incorporation fee increased to £100 on 1 February 2026, while the digital confirmation statement fee increased to £50.
Accountancy and bookkeeping costs vary depending on transaction volume, payroll, VAT registration and the complexity of the business.
Although limited companies involve greater administration, these costs may be justified where the structure provides important commercial or legal advantages.
How Do Liability And Legal Responsibilities Differ?
Liability is a major consideration when deciding how to structure a business.
A sole trader is personally responsible for business debts and contractual obligations. If the business cannot meet its commitments, creditors may pursue the owner’s personal assets, subject to relevant legal protections.
For example, a self-employed tradesperson who takes out a business loan may remain personally responsible for repaying it even if the business closes.
A limited company has a separate legal identity. Its liabilities are normally the company’s responsibility rather than the personal responsibility of its shareholders.
However, limited liability does not offer complete protection.
Directors may still face personal exposure through:
- Personal Guarantees: Agreeing to repay company borrowing personally.
- Wrongful Or Fraudulent Trading: Continuing or conducting business in circumstances that breach insolvency law.
- Breach Of Directors’ Duties: Failing to comply with relevant legal responsibilities.
- Personal Misconduct: Acting unlawfully or improperly in ways that create personal liability.
Business owners should also consider insurance, contractual risks and borrowing arrangements rather than relying entirely on the chosen legal structure.
What Are The Accounting And Making Tax Digital Requirements?
Sole traders and limited companies have different obligations for record-keeping, tax returns and financial reporting.
Sole traders generally maintain records of income and allowable expenses, submit Self Assessment returns when required and pay applicable Income Tax and National Insurance.
Limited companies must keep appropriate accounting records, prepare annual accounts and comply with Corporation Tax requirements. They must also submit confirmation statements and meet relevant Companies House filing deadlines.
Making Tax Digital For Sole Traders
Making Tax Digital for Income Tax is being introduced in stages based on qualifying income from self-employment and property.
| Start Date | Qualifying Income Threshold |
| 6 April 2026 | More Than £50,000 |
| 6 April 2027 | More Than £30,000 |
| 6 April 2028 | More Than £20,000 |
Qualifying income generally refers to gross income before expenses, not business profit. Those within the scheme must maintain digital records, use compatible software and provide required updates.
These Making Tax Digital for Income Tax thresholds do not apply to limited companies in the same way. Companies have separate Corporation Tax and accounting obligations.
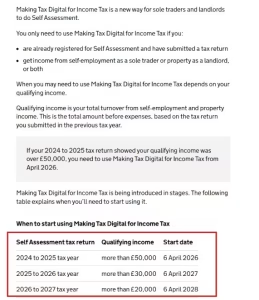
HMRC’s Making Tax Digital guidance confirms the qualifying income thresholds and phased start dates from April 2026 to April 2028.
VAT Registration Requirements
Both sole traders and limited companies generally need to register for VAT when taxable turnover exceeds £90,000 over a rolling 12-month period or is expected to exceed that amount within the next 30 days.
Businesses below the threshold may register voluntarily.
Understanding how to register for VAT is important regardless of business structure, particularly where turnover is increasing or the business regularly purchases VATable goods and services.
Limited company directors should also account for mandatory Companies House identity verification requirements introduced in November 2025.
Which Business Structure Is Better For Freelancers And Small Businesses?
Different business activities have different financial and legal risks. The best structure therefore depends on more than annual income.
| Business Type | Structure Worth Considering | Main Reason |
| Part-Time Freelancer | Sole Trader | Simple Setup And Lower Administration |
| Independent Designer | Sole Trader Or Limited Company | Depends On Income And Client Requirements |
| IT Contractor | Either | Depends On Tax, Contract Terms And IR35 |
| Online Shop | Either | Depends On Turnover, Product Liability And Growth |
| Consulting Agency | Limited Company | Can Support Shareholders And Expansion |
| Local Service Provider | Sole Trader | Often Suitable For Smaller Operations |
| Growing Technology Startup | Limited Company | May Support Equity Investment |
For example, a freelance writer earning £20,000 annually may prefer the simplicity of sole trader registration.
However, an entrepreneur developing a technology business with multiple founders and plans to attract investors may find a limited company more appropriate from the beginning.
Contractors must also consider employment status and the off-payroll working rules, commonly known as IR35, where relevant.
The decision should reflect personal circumstances, liability exposure, future ownership plans and administrative costs.
When Should You Change From Sole Trader To Limited Company?
Many entrepreneurs begin as sole traders and incorporate once their business becomes more established.
There is no fixed income level at which incorporation becomes compulsory or automatically more tax-efficient.
However, switching may be worth considering when:
- Business Profits Increase: Reviewing whether a company offers better financial flexibility becomes worthwhile.
- Financial Risks Grow: Larger contracts, borrowing or operational liabilities increase the importance of legal protection.
- Investment Is Required: Incorporation can allow shares to be issued to suitable investors.
- Business Expansion Begins: A company may offer a more suitable ownership and management structure.
- Profits Are Being Reinvested: Retaining earnings within a company can offer different tax-timing opportunities.
How To Switch From Sole Trader To Limited Company?
Changing business structures involves more than simply changing the name on invoices.
The main steps generally include:
- Register The Company: Incorporate the new legal entity with Companies House.
- Arrange Business Banking: Establish suitable banking arrangements for the company.
- Inform HMRC: Report the relevant changes to your business and tax status.
- Transfer Business Assets: Review equipment, stock, intellectual property and other assets being transferred.
- Update Contracts And Invoices: Ensure customers and suppliers understand which legal entity they are dealing with.
- Review VAT Registration: Apply for a new registration or arrange a transfer where appropriate.
- Set Up Company Accounting: Prepare for Corporation Tax, statutory accounts and any payroll obligations.
Anyone planning the transition should understand how to register a company in the UK and consider professional advice before transferring significant assets or contracts.
Incorporation can create Capital Gains Tax, VAT or other tax consequences, depending on how the business is transferred.
Which Is More Tax-Efficient: Sole Trader Or Limited Company?
The tax efficiency of each structure depends on how much profit the business generates, how much money the owner needs personally and what happens to any remaining earnings.
A sole trader pays Income Tax and National Insurance on taxable profits, even when some of those profits remain in the business bank account.
A limited company pays Corporation Tax and can retain post-tax profits for future business activities. Personal dividend tax is generally triggered when taxable distributions are made to shareholders, not simply because profits remain within the company.
This distinction can make incorporation attractive where profits are not immediately required for personal spending.
However, if the owner withdraws nearly all available profits each year, the combination of Corporation Tax, salary-related costs and dividend tax can reduce or eliminate potential tax advantages.
For that reason, businesses should compare:
- Total Annual Profit: The amount earned after allowable operating expenses.
- Personal Income Requirements: How much money the owner needs to withdraw.
- Corporation Tax And Dividend Tax: The combined impact of company and shareholder taxation.
- Employer National Insurance: Whether director salary payments create additional costs.
- Accounting And Filing Expenses: The extra costs associated with maintaining a company.
- Future Investment Plans: Whether profits will be retained to finance business growth.
A personalised calculation is more reliable than assuming a limited company becomes preferable above £20,000, £30,000 or any other fixed profit threshold.
Conclusion
Choosing between a sole trader and a limited company involves balancing simplicity, taxation, liability and future business plans.
Sole trader status is often suitable for freelancers and smaller businesses that want straightforward registration, fewer reporting obligations and direct access to earnings.
A limited company may be more appropriate where owners need a separate legal identity, expect to introduce shareholders, plan to retain profits or want to manage business risks through incorporation.
Before making a decision, compare the total tax burden, administration costs, potential liabilities and long-term objectives. The right structure should support both the current needs and future development of the business.
Frequently Asked Questions
Is It Better To Be A Sole Trader Or Limited Company In The UK?
A sole trader is often better for simplicity and lower administration costs, while a limited company may provide advantages for growing businesses, shareholders and liability management.
At What Income Should I Become A Limited Company?
There is no fixed income threshold. Incorporation becomes worth reviewing when profits, risk exposure, personal income needs or future investment plans make a company structure more suitable.
Can One Person Run A Limited Company?
Yes. A UK private limited company can generally have one director and one shareholder, and both roles can be held by the same person.
Can I Be A Sole Trader And Own A Limited Company?
Yes. You can operate as a sole trader while also owning a limited company, provided the activities and financial records are managed correctly.
Can A Sole Trader Employ Staff?
Yes. Sole traders can employ workers and must meet relevant employment law, payroll, National Insurance and workplace pension obligations.
Is It Cheaper To Run A Sole Trader Business Or Limited Company?
A sole trader business is generally cheaper to administer because it has fewer statutory filing requirements. Limited companies usually have higher accounting and compliance costs.
Can I Change From Sole Trader To Limited Company Later?
Yes. You can incorporate a company and transfer business activities, although you may need to update contracts, banking arrangements, tax registrations and ownership of business assets.